If you have spent years building a business, you likely have a good sense of what it is worth and who helps keep it running. What is harder to pin down, and often gets put off, is what should happen to the company on the day you step back, whether that happens through retirement, an illness, or an unexpected event.
Even when you do not write down a plan, Texas law still applies one. Those default rules come from the Business Organizations Code and the Estates Code, and because they are written as general rules for everyone, they rarely match what a family or business owner actually wants.
What does Texas law do if you have no plan?
Three default rules come into play at the same time, and together they can create real complications for your family and co-owners.
Your spouse probably already owns half. If you built or acquired the business during your marriage, your ownership interest is generally community property. That means half of it already belongs to your spouse, and your will can only direct what happens to your half.
Your heirs inherit the financial interest, not the vote. Under Texas Business Organizations Code §101.1115, when an LLC member passes away, the surviving spouse, heirs, and personal representative become assignees of the membership interest. They are entitled to receive distributions and a share of profit, but they cannot vote, participate in management, or require the remaining owners to buy them out. That can leave your remaining partners working alongside a family member who has a financial stake without management rights, and your family holding an interest they cannot easily sell. A written company agreement can replace this default rule with terms you choose.
If there is no will, your share may not go to your spouse. Under Texas Estates Code §201.003, if you pass away without a will and have a child from outside your current marriage, your half of the community property passes to your children. Combined with the assignee rule, the business can end up co-owned by adult children who have no voting rights and no clear path to a buyout.
When does a business change hands?
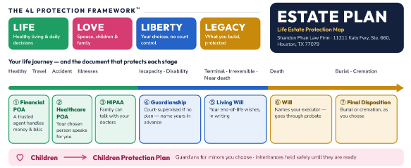
Passing away is only one of the four situations where ownership or control of a business changes, and it is not the most common one:
- Retirement gives you the opportunity to transition the company thoughtfully on your own timeline, though many owners delay putting the terms on paper.
- Disability or health decline can be difficult because there is rarely a single clear date when it begins, so someone needs legal authority to sign and make decisions before that moment arrives.
- Death, where the Texas default rules described above take effect unless you have planned ahead.
- A split between owners, including divorce, since §101.1115 applies to divorce as well as death and can leave a former spouse holding an assignee interest in the company.
A succession plan that only addresses death leaves the other three situations uncovered.
What is a buy-sell agreement, and what changed in 2024?
A buy-sell agreement is a contract signed by the owners in advance that sets out what happens to an ownership interest when a triggering event occurs: who has the right or obligation to buy, who must sell, how the interest is valued, and where the funds will come from. It works for an LLC, a corporation, or a partnership, and it is binding on heirs, which closes the gap left by §101.1115.
Many buy-sell agreements are funded with life insurance, and an important federal tax rule changed in 2024. In Connelly v. United States, decided unanimously on 6 June 2024, two brothers owned a company that held life insurance on each of them to fund a share buyback. When one brother passed away, his family reported his shares at $3 million, while the IRS valued them at $5.3 million and assessed $889,914 in additional estate tax. The Supreme Court agreed with the IRS, holding that life insurance proceeds payable to the company increase the company’s value and are not offset by the company’s obligation to buy back the shares.
If your buy-sell agreement was drafted before June 2024 and the company itself owns the life insurance policies, it may rely on the valuation assumption that the Supreme Court rejected. Other arrangements, such as a cross-purchase agreement where the individual owners hold the policies, can avoid that result, and the right structure depends on how many owners are involved, their ages, and what coverage is already in place.
Will your family owe estate tax on the business?
Most families will not. Texas does not have a state estate tax or a state income tax. For 2026 deaths, the federal estate tax exemption is $15,000,000 per person, and a married couple can generally make use of both exemptions, while the annual gift tax exclusion for 2026 is $19,000 per recipient. Figures current for 2026.
For most Texas family businesses, the bigger financial concerns are liquidity and tax basis. Liquidity matters because cash may be needed to pay a departing co-owner, satisfy a lender calling a personal guaranty, or compensate a family member at a time when the business does not have extra cash on hand. Tax basis matters because the way an ownership interest passes determines whether your heirs receive a stepped-up tax basis or carry over your original cost basis.
What if long-term care is on the horizon?
If you or your spouse may eventually need Medicaid to help pay for long-term care, your business interest is generally treated as a countable resource unless an exclusion applies, and after death the Medicaid Estate Recovery Program can make claims against assets in the estate. Texas offers a hardship waiver for an income-producing business, though under rules amended effective 27 August 2026, the business must have operated at that location for at least twelve months and provide at least half of the applicant’s livelihood.
Medicaid also reviews asset transfers made during a five-year look-back period. Transferring the business directly to your children as a quick fix can create a Medicaid penalty period while also leaving you without control or income, so it helps to look at both issues together before making any changes.
The conversation most families put off
Putting the legal paperwork together is often the more straightforward part. What takes more thought is talking through the practical family questions that determine whether a transition goes smoothly:
- Which of your children is prepared to run the business, and do they actually want to take it on?
- How do you treat children who are not involved in the business fairly when the company makes up most of what you own?
- If your spouse relies on income from the business but has not worked in it, what income should they receive and who will manage operations?
- Is there a partner, sibling, or relative whose role everyone understands informally, but nothing has ever been put in writing?
- If none of your family members wants to run the business, is there a realistic buyer, and what would the company be worth without you there?
For Vietnamese-owned family businesses
Many of the businesses we advise were built by family members working together rather than through formal corporate paperwork: salons, restaurants, grocery stores, repair shops, and rental properties held among relatives. In many cases, everyone understands who owns what, but nothing was ever recorded. Everything may run fine until someone passes away, at which point there is no written document showing what everyone agreed to. Putting those terms on paper is not a sign of distrust; it is simply the clearest way to make sure the arrangement your family agreed upon is the one the law will follow. Chúng tôi tư vấn bằng tiếng Việt.
Start here
You can book a consultation using the form on this page or call or text (281) 407-5622. If you would like to see where your current plan stands first, you can also take the free 4L Family Protection Audit.
Questions we get
What happens to my LLC in Texas if I die without a plan?
Under Texas Business Organizations Code §101.1115, your surviving spouse, heirs, and personal representative become assignees of your membership interest. That allows them to receive financial distributions, but they do not become members and cannot vote or manage the company unless a written company agreement changes that rule.
Does my spouse automatically inherit my share of the business?
Not always. If the business was built during your marriage, your spouse generally already owns half as community property, and your will only controls your half. If you die without a will and have a child from another relationship, Texas Estates Code §201.003 passes your half of the community property to your children.
How did Connelly v. United States change buy-sell agreements?
In 2024, the U.S. Supreme Court ruled that life insurance proceeds payable to a company increase the company’s value for estate tax purposes, and that the company’s obligation to buy back a deceased owner’s shares does not reduce that value. If you have a company-owned, insurance-funded buy-sell agreement written before June 2024, it is a good idea to have it reviewed.
Should I just put the business in my children’s names now?
In most cases, transferring ownership outright too early causes more issues than it solves. A transfer within the five-year Medicaid look-back period can trigger a penalty, your children’s personal creditors or divorces could affect the business, you give up control over an asset you may still rely on, and your heirs may lose the step-up in tax basis.
We never wrote anything down. Is it too late?
No, it is not too late as long as everyone involved is still able to sign. Putting an existing understanding in writing now is much easier than trying to sort out or prove an informal arrangement later.